
October 29, 2026
Starting Over With Another Adjuster: What LA County Alleges Against State Farm
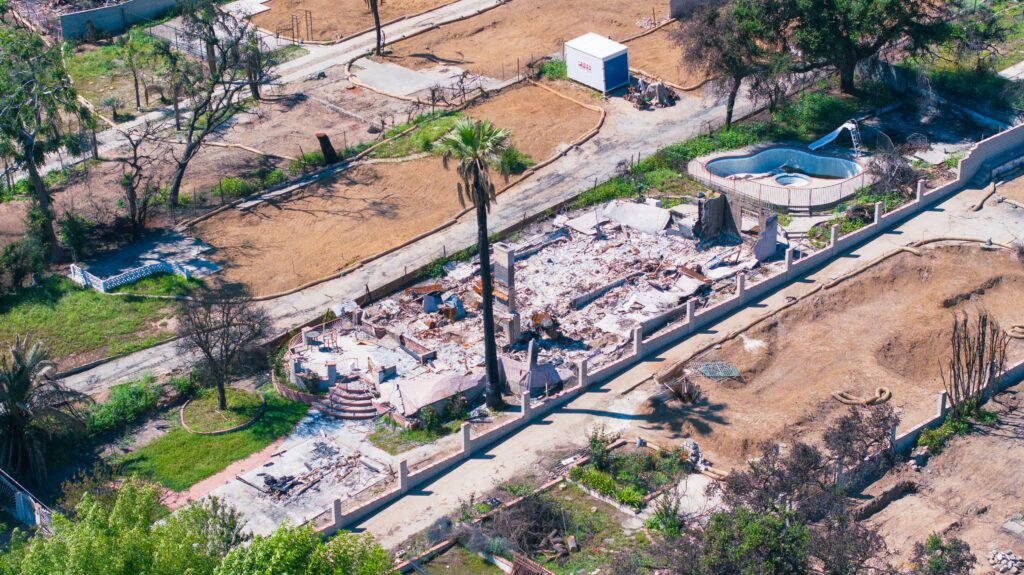
A homeowner should not have to explain the same loss from the beginning every time an insurance company changes the person handling the claim. That problem is one focus of Los Angeles County’s lawsuit over State Farm’s handling of wildfire claims.
The county announced the lawsuit on August 31, 2026, alleging delays, underpayments and denials following the January 2025 Eaton and Palisades fires. It seeks restitution for affected policyholders and other relief. State Farm disputes the county’s characterization.
When a new adjuster means starting again
The county’s complaint, particularly pages 6 and 26, describes reports from survivors of repeated adjuster changes, stalled claims and disputed verbal commitments. Those accounts are allegations presented by the county, not findings made by a court.
There is a practical difference between assigning a new contact and making a homeowner rebuild the entire conversation. Who has the documents? Which questions were already answered? Does the new person recognize the work the previous person reviewed? Those are the questions this part of the lawsuit brings into focus.
The cost of a stalled conversation
The complaint also alleges that delays in temporary living expense payments pushed families to use their own money while displaced. Its accounts connect communication problems with the everyday difficulty of finding a place to stay. We have not independently verified each family’s account.
For a homeowner, a delay is measured in more than unanswered messages. It can mean another housing decision that cannot wait for the next returned call. That is why a claim’s handling deserves scrutiny alongside the final estimate.
State Farm’s response
In its August 31 response, State Farm General said it strongly disagreed with the county’s account and would respond through the legal process. The company said it had paid more than $6.2 billion on the Los Angeles wildfire claims, including about $1 billion for smoke damage, and closed about 78% of claims. These are the company’s figures as of that statement, not an October update.
What this report establishes
The county has brought allegations, and the insurer has publicly disputed its characterization. This article explains those positions. It does not report a judgment, a settlement or a finding that every disputed claim was handled improperly. The cited material does not establish a later case outcome.
Our focus is the homeowner’s experience when an insurance process becomes another obstacle after a loss. Future coverage will examine specific disputes and the evidence behind them, including the insurer’s response, rather than treating the filing of a lawsuit as proof of wrongdoing.